

Dollarbird Pro
by Dollarbird Apps SRL
3.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.3
- Price
- Free
- Download
- 50.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
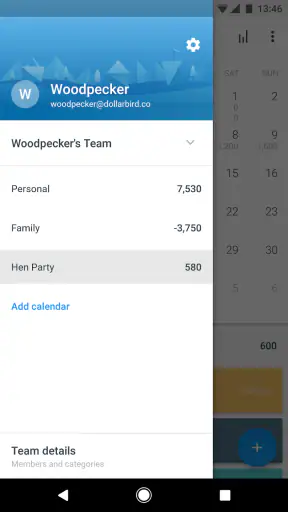
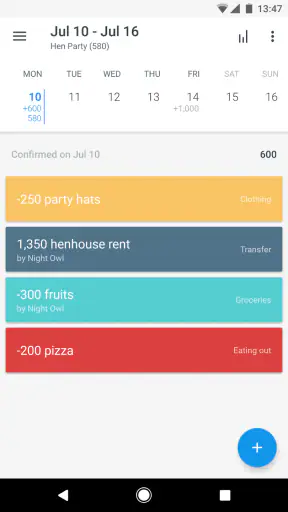
 Analysis by Getfullapps
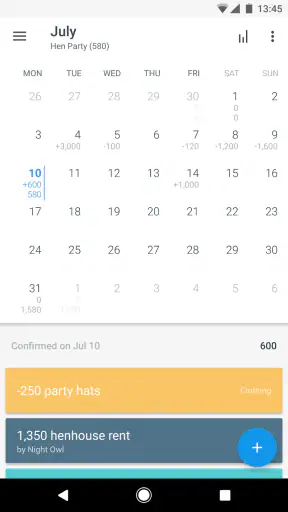
I like finance apps that make me look at my money before it disappears, and Dollarbird Pro takes a clear, visual route: it turns personal budgeting into a calendar. That simple choice is the heart of the experience. Instead of forcing every expense into a long list or a collection of charts, it asks me to think in dates, upcoming bills, and the balance I expect to have later. For people who plan around paydays, rent, subscriptions, and irregular expenses, that can feel much more natural than traditional budgeting tools.
My overall view is positive but specific. This is not the best choice for someone who wants automatic bank synchronization, investment tracking, or a highly detailed accounting system. It is more useful as a forward-looking cash-flow planner: a place to enter what is coming, see how those entries affect the calendar, and notice a difficult week before it arrives. The app is free to start, carries an Everyone age rating, and comes from Dollarbird Apps SRL. Its current Android version is 6.2.2, with Android 6.0 or newer required.
Why the calendar approach works better than a normal expense list
The strongest part of Dollarbird Pro is the way time becomes the main organizing idea. In a conventional expense tracker, I usually record what has already happened and then inspect categories afterward. Here, the more valuable habit is to place expected income and spending on their actual days. That changes the question from “Where did my money go?” to “What will my balance look like when these commitments arrive?”
That distinction matters in everyday life. Imagine being paid near the end of the month while rent, utilities, and a yearly insurance payment fall at different points in the following weeks. A list can show all those amounts, but a calendar makes the spacing visible. I can identify the moment when the balance becomes uncomfortable, even if the month looks affordable overall. That is a practical advantage, especially for people whose problem is timing rather than a complete lack of income.
The app’s store summary describes it as a personal finance calendar with an AI element. I would treat that “spark of AI” as an extra layer rather than the reason to install it. The core value still comes from entering useful information consistently and interpreting the resulting schedule. No intelligent suggestion can rescue a calendar that is missing the recurring payment I forgot to add.
Once I adopt the calendar mindset, the app becomes particularly suitable for planning variable costs. Groceries, transport, school expenses, medical appointments, travel, and annual renewals do not always fit neatly into a fixed monthly budget. Putting them on the dates when I expect them gives the forecast more realism than simply dividing an annual amount by twelve.
Entering information with a purpose
A common mistake with planning apps is to record every tiny purchase and then abandon the routine because it feels like bookkeeping. Dollarbird Pro can be used that way, but I think it is more effective when I decide what level of detail will actually improve a decision. Fixed bills deserve precise entries. Flexible spending can be represented with sensible estimates. The goal is not to create a perfect historical ledger; it is to make the future easier to read.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For example, I would record a regular rent payment on its due date, add a realistic grocery allowance for the week, and enter a known birthday or travel expense before it becomes urgent. I would not spend the same effort documenting every small snack unless that information helped me change a habit. This selective approach is one of the app’s less obvious strengths: the calendar remains useful when it reflects decisions, not just receipts.
Another practical workflow is to review the next several weeks at the same time each week. I can move from broad planning to a short checklist: which payments are fixed, which amounts are estimates, and where the balance may become tight. That review is more valuable than opening the app only after a purchase has already happened. The calendar is at its best when it becomes a planning appointment rather than a passive archive.
Where the visual forecast earns its place
The calendar format is especially helpful for people with uneven income. Freelancers, part-time workers, seasonal employees, and households with more than one payday often need to know whether money arrives before a major expense. A monthly category budget may say that the total is acceptable, while the calendar reveals a short-term gap. That is the kind of problem a forward schedule can expose early enough to solve.
It can also help couples or families discuss money without beginning with blame. Instead of arguing over a vague feeling that the month is expensive, we can look at the dates that create pressure. One person may be paid earlier, another may handle a particular bill, and a shared calendar can make the sequence easier to understand. I would still agree on who enters and updates each item, because a shared plan becomes unreliable if everyone assumes someone else maintains it.
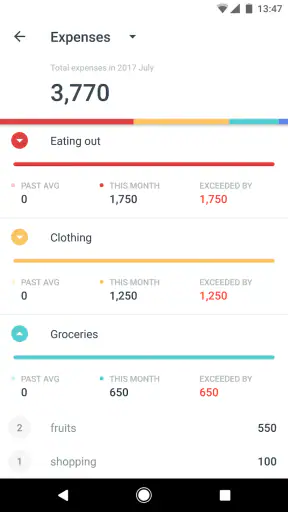
There is a useful trade-off here. A calendar is intuitive for timing, but less immediately powerful for analyzing spending patterns. If I want to know exactly how much I spend on restaurants compared with transport over a long period, a category-first finance app may give me a clearer answer. Dollarbird Pro is strongest when the question includes “when,” not only “how much.”
What I would check before relying on it
The meaningful weakness is that the quality of the forecast depends heavily on manual discipline. The app can make future money visible, but it cannot automatically know every cash expense, changed bill, delayed payment, or unexpected purchase unless I keep the calendar current. That creates friction for anyone who expects a finance app to build a complete picture without regular input.
This is also where the product differs from bank-connected alternatives. Automatic transaction import can reduce the work of recording completed purchases, while Dollarbird Pro’s calendar approach asks me to think ahead and maintain expected entries. Neither method is universally better. Automatic imports are convenient for historical accuracy, but they may show a problem only after it occurs. Manual forecasting is more proactive, but it requires attention and honest estimates.
I would therefore avoid treating the displayed future balance as a promise. It is a planning model. If I enter an optimistic grocery estimate or forget an annual charge, the result can look reassuring while being wrong. The right habit is to leave some breathing room and update estimates when real costs become clearer. That is not a flaw unique to this app, but the calendar format can make a precise-looking forecast feel more certain than it really is.
There is another limitation for advanced users. Someone who needs tax records, detailed account reconciliation, debt amortization, investment performance, or business bookkeeping will likely outgrow this approach. The app belongs in the personal planning part of the finance category, not as a replacement for full accounting software. I would also choose a different tool if automatic bank connections are the main reason I want a finance app.
Free access and the Pro question
Dollarbird Pro is listed as free, with in-app purchases ranging from $7.99 to $79.99 per item. That makes the first step relatively easy: I can test whether the calendar habit suits me before committing money. The important question is not simply whether the app costs nothing to install, but whether the functions I need are available in the free experience or sit behind the paid options.
I would approach the purchase carefully. First, I would create a realistic planning routine, add the bills that matter most, and use the calendar long enough to see whether it changes my decisions. If I stop opening it after a few days, paying will not solve the underlying habit problem. If it becomes the place I genuinely use to prepare for upcoming expenses, a paid option may make sense, depending on which Pro capabilities I need.
The pricing range is broad enough that users should read the purchase screen closely before confirming anything. I would pay attention to whether an option is a one-time purchase or a recurring arrangement, and I would check exactly what is unlocked. That advice is especially important for a budgeting app: the cost of the tool should fit the financial control it helps create.
Small habits that make the forecast more trustworthy
My first tip is to enter recurring commitments before discretionary spending. Rent, utilities, memberships, loan payments, and planned transfers establish the shape of the month. After that, add flexible costs. If I begin with coffee and shopping while leaving a major bill out, the calendar may look active but still fail at its main job.
My second tip is to separate certainty from approximation in my own thinking. A fixed bill can be entered as a known amount, while electricity, groceries, or fuel may need a cautious estimate. I would rather slightly overestimate a variable expense than build a forecast that only works under perfect conditions. The app cannot make that judgment for me, so the usefulness of its visual output depends on the assumptions behind each entry.
My third tip is to use the calendar before making a nonessential purchase, not only afterward. If I am considering a large weekend expense, I can look at the days immediately following it and see whether a bill is due before the next income arrives. This turns the app into a decision filter. It does not tell me what I am allowed to buy; it shows the timing cost of buying it now.
A fourth useful habit is to review old estimates rather than endlessly adding new ones. If a recurring expense is consistently higher than expected, correcting the amount improves every future view. If an event has passed, checking whether the estimate was realistic teaches me how conservative the next forecast should be. That feedback loop is more valuable than simply filling the calendar with more entries.
Who should use it, and who should skip it
I would recommend this app to someone who thinks in pay cycles and due dates, especially a person who regularly reaches the end of a month wondering why the balance feels tight. It is also a good fit for a household that wants a shared visual plan, provided everyone agrees to maintain it. People who dislike spreadsheets may appreciate the calendar because it connects money to familiar days instead of presenting a wall of figures.
It is less suitable for users who want a completely automatic experience. If the ideal finance app is one that connects to every account, imports transactions, categorizes them, and produces reports without much effort, I would look elsewhere. I would also skip it for business finances or complicated investment monitoring. Its focused design is an advantage for simple personal planning, but that focus becomes a boundary when financial needs become more technical.
The public response suggests a mixed but meaningful level of interest: Dollarbird Pro has a 3.3 average from around 592 ratings, along with more than 128 written reviews and over 50K installs. Those figures do not change my practical assessment, but they do place the app in a realistic context. It is not a universally loved solution, and prospective users should be comfortable with the manual calendar method rather than expecting a magic financial assistant.
Its Everyone rating also makes it approachable for a broad audience, although suitability still depends on financial complexity and personal habits. A younger user learning to plan bills, an adult managing irregular income, or a couple coordinating expenses may all use the same calendar differently. The app does not need to be complicated to be useful, but it does need consistent attention.
My final take after weighing the trade-offs
Dollarbird Pro succeeds because it gives a difficult personal finance question a concrete shape: what happens to my money across the coming days? I find that more actionable than a backward-looking list when I am preparing for bills, uneven income, or a crowded month. The calendar encourages me to notice timing, and that alone can prevent avoidable surprises.
At the same time, I would not recommend it as a complete financial command center. Its manual nature demands a routine, its estimates need sensible margins, and users seeking automatic account data or advanced reporting will probably be happier with another category of tool. The app is not a substitute for financial judgment; it is a clear surface on which to apply it.
My recommendation is simple: choose Dollarbird Pro if your biggest money problem is timing, not a lack of reports. Start with the free version, enter the commitments that genuinely affect your month, and test whether the calendar changes your choices. If you enjoy planning ahead and keep the entries current, this focused finance app can become a practical weekly guide. If manual updates already sound exhausting, the usual automated alternatives will likely serve you better.
Pros
- Calendar-based design makes future cash flow easy to visualize.
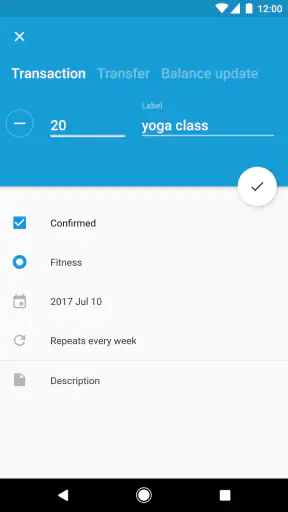
- Supports recurring transactions for regular income and expenses.
- Useful for planning bills, savings goals, and upcoming purchases.
- Color coding helps distinguish spending categories at a glance.
- Works well for users who prefer manual control over their finances.
Cons
- Manual entry can become time-consuming for frequent transactions.
- No automatic bank syncing may limit convenience for some users.
- Shared finances may require extra coordination between household members.
- Detailed budgeting features may feel limited for advanced users.
- Accurate results depend on consistently recording every transaction.
FAQs for Dollarbird Pro
What is Dollarbird Pro used for?
Dollarbird Pro is a personal finance and budgeting app designed to help you track income, expenses, bills, and upcoming financial commitments in one calendar-based view. Instead of only showing past transactions, it helps you understand how today’s spending may affect your future balance. It can be useful for organizing household finances, monitoring recurring payments, and planning cash flow before making larger purchases.
How does the calendar-based budgeting system work?
The app organizes financial activity by date, allowing you to add transactions and see when money is expected to enter or leave your account. You can record recurring expenses, planned purchases, and income to create a forward-looking cash-flow calendar. This approach is especially helpful if you prefer visual planning, although the accuracy of projections depends on keeping your entries updated and realistic.
Does Dollarbird Pro connect directly to bank accounts?
Before downloading, users should check the current store description and in-app settings to confirm which account-connection features are available in their region and version. Dollarbird has traditionally focused on manually entered financial information rather than relying entirely on automatic bank synchronization. If you want fully automated transaction imports, verify this carefully, because manual tracking may require more regular effort than conventional banking apps.
Is Dollarbird Pro suitable for shared or family budgeting?
Dollarbird Pro can be useful for couples, families, or small teams who want to coordinate planned spending, provided the version you install includes the collaboration features you need. Shared financial planning works best when everyone records transactions consistently and agrees on categories and account balances. Users should also review privacy, invitation, synchronization, and subscription details before adding sensitive household information or relying on it for important financial decisions.
Is Dollarbird Pro free, and is it safe to use?
Availability, pricing, and included features may vary between Android, iOS, and different subscription plans, so review the official store listing before downloading. The app is a budgeting tool, not a bank or financial adviser, and it should not replace official account records. For safety, use a strong device password, install updates from the official store, review permissions and privacy policies, and avoid entering information you are not comfortable storing in a third-party service.

Dollarbird Pro
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hello@dollarbird.co, visit http://dollarbird.co, or review their https://legal.dollarbird.co/pp.html.










